What is credit mix + how does it affect your credit score?
February 28, 2023

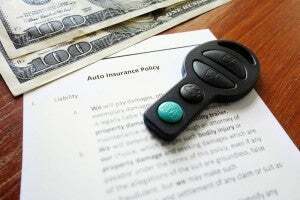
Consumer Reports just released the results of its 2-year investigation which found that poor credit may raise auto insurance premiums higher than even a drunk driving conviction.
Yes, that’s right.
See for yourself. According to the investigation, listed below are the premiums for a single driver with a clean driving record depending on their credit history. At the bottom of the chart, the premiums are compared to a single driver with excellent credit and a DWI (all in Florida):
| Excellent Credit | $1409 |
| Good Credit | $1721 |
| Poor Credit | $3826 |
| Excellent Credit & with a DWI | $2274 |
What the auto insurance premium investigation uncovered about the use of credit history
I’ve written before about how your credit history can be used in ways that have nothing to do with borrowing money such as determining your premiums for car insurance. This Consumer Reports investigation, which began in 2013, collected more than 2 billion price quotes from 19 insurance carriers in each state representing 20 hypothetical driver/consumer profiles over the last 2 years. It included all of the top carriers such as Allstate, Progressive, Geico, State Farm and USAA.
I wrote recently how 92% of auto insurance companies use a specialized, proprietary insurance score (not your FICO score) which is based on the information in your credit reports as part of their underwriting process to determine the chance that you will get in an accident and make a claim on the policy. But the Consumer Reports investigation found (when comparing premiums by credit ratings in the consumer profiles) that those with poorer credit history were actually offered heftier premiums, even if they’d never had an accident. And it’s not a standard surcharge nor is it small. The report found, for example, that single drivers with just “good” credit (compared to the “best” credit) averaged paying $68 to $526 more per year depending on their state.
The most surprising thing the investigation uncovered was that your credit history could affect your premiums even more than your driving history. The example cited in the report: For single Kansas drivers, one moving violation increased the premium by an average of $122 per year but drivers with just “good” credit history instead of the “best” credit history were raised an average of $233, even with a perfect driving record. Even worse, if your credit is “poor”, the average premium hike was $1,301.
Basic good credit advice is the best advice for auto insurance scoring too
Bottom line: If you pay your accounts late, have accounts in collection or maxed out credit cards, even if you pay on time, these are all tip-offs to the insurance companies that you might not manage your money very well, and thus are at greater risk for a car accident or making a claim on your auto insurance policy.
The investigation found that insurers do not have to tell you what score they actually used or how it was tabulated, so there’s no way to know how they are scoring you specifically (although they must notify you if they are raising your rates due to information in your credit report.) The best advice is basic good credit advice which is to pay bills on time, keep credit usage low and never default on an account so it goes to collections.
Here’s what the report found you can do about unfair auto insurance premium pricing based on credit history:
The Consumer Reports Investigation uncovered many more unfair pricing tactics in the auto insurance industry that you may have no control over, but you can control about what they see in your credit report.